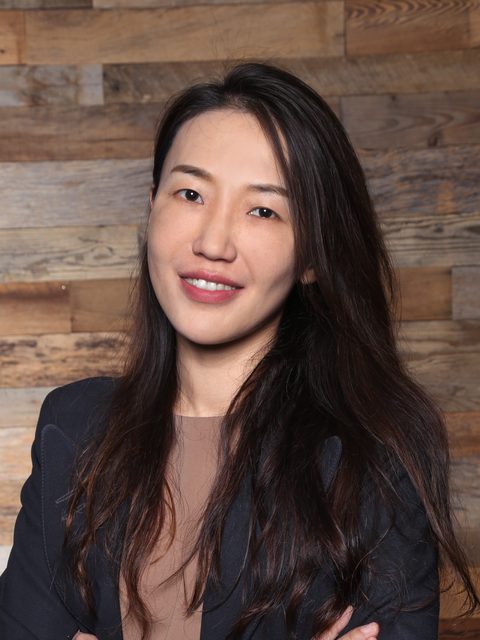
I study how financial intermediaries—mutual funds, insurers, and FinTech lenders—shape capital allocation, corporate borrowing costs, and the information investors receive, and how corporate disclosure is changing as AI becomes part of the audience. Before academia I worked in open-market operations at the Central Bank of the Republic of China (Taiwan) and in risk management at Yuanta Financial Holding.
Research
Financial intermediaries, mutual funds, FinTech, fixed income, and AI.
Revise and resubmit
Democratized Access, Preferred Allocation: Quid Pro Quo and Regulatory Scrutiny in Marketplace Lending
Abstract
Marketplace lending platforms (MLPs) act as intermediaries between borrowers and investors, facilitating the creation of unsecured consumer loans. We examine how MLPs allocate loans between retail and institutional investors. Controlling for observable risk factors, including interest rates, we find that strategic allocation varies with origination volume. Specifically, institutional investors receive loans with 8.0% lower default rates when volume is low, while retail investors receive higher-quality loans when volume is high. This time-varying pattern reflects MLPs balancing quid pro quo incentives with the costs of regulatory scrutiny. We document additional preferential treatment among institutional investors, where balance-sheet lenders receive higher-quality loans than pass-through investors (such as hedge funds and investment banks) during periods of asset-backed securities accumulation. Using the 2015 San Bernardino shooting as an exogenous shock to regulatory intensity, we provide evidence that intermediary allocation strategies respond to regulatory pressure. Our findings reveal how emerging FinTech intermediaries navigate traditional financial incentives and regulatory oversight, with implications for the protection of retail investors and the design of financial markets.
Presented at SFS Cavalcade, Cambridge Alternative Finance, Bergen FinTech, MFA, China FinTech Research Conference, FMA, AFA PhD Session, Toronto FinTech.
Fund Family Diversification and Common Flow Risk Hedging
Abstract
This paper examines the effect of family-level product diversification on equity-common-flow risk hedging. We document that due to low correlations among common flows to various asset classes, product diversification reduces family-wide flow volatility. Consequently, fund managers of more diversified families hedge less against equity common flow shocks. This effect is absent for externally managed funds, suggesting the internal compensation structures influence managers’ hedging decisions. Furthermore, common flow risk premium is significantly higher for stocks held by funds in concentrated families than for stocks held by funds in diversified families. Our study underscores how family-level product diversity affects managers’ incentives and their portfolio decisions.
Presented at FMA Asia, FMA, Bentley Joint Conference on Accounting, Economics and Finance, UC Irvine, Taiwan Economic Research, National Chengchi University.
Working papers
Gender Disparities in the Mutual Fund Industry: Investor Flows, Selection Bias, and Managerial Skill
Abstract
This paper examines the structural barriers behind the underrepresentation of women in the US equity mutual fund industry. Using data from 1992 to 2022, we document a Glass Cliff in appointments: female managers are disproportionately assigned to funds with poor historical performance. We also document a demand-side friction that we argue produces it: investors translate a female manager’s performance into capital less strongly than a male manager’s. The flow-performance relation flattens after a woman is appointed, and flattens most when she replaces a departing man, while pre-appointment sensitivity does not predict who is appointed. This muted response is not the efficient discounting of a noisier signal: past performance forecasts future performance equally well regardless of manager gender. Post-appointment performance is likewise indistinguishable across genders, leaving no skill gap for the pattern to reflect. A small modification of the Berk–Green (2004) model of delegated portfolio management adds a gender-dependent slope to the flow-performance relation. It rationalizes these facts jointly and shows why they are connected. Because a flatter response forfeits inflows at strong funds and cushions redemptions at weak ones, the model gives fund families an incentive to assign women to weaker funds. Taken together, our model and evidence support a view of the Glass Cliff as fund families’ response to gendered information processing by investors, rather than an independent supply-side friction.
Supported by the W. Michael Hoffman Center for Business Ethics. Presented at National Taiwan University and Bentley; scheduled for the EUROFIDAI-ESSEC Paris Finance Meeting and the HCBE 50th Anniversary Conference.
Evolution of Corporate Disclosure in an AI-Mediated Information Environment
Abstract
This paper documents a structural shift in U.S. corporate disclosure following the availability of large language models (LLM) in 2022. Using MD&A filings from 2015–2025, we estimate a difference-in-differences specification pairing each firm’s original filing (treated) with its own GPT-generated summary (control). The result is a sharp, post-2022 expansion of the cognitive thinking process, rising 28–34% of a sample standard deviation relative to the machine baseline, an economically large shift in a sticky textual domain. This expansion is accompanied by a mirror-image collapse in authenticity and emotional tone. These findings suggest that firms inflate cognitive content to preserve managerial reasoning under algorithmic compression while neutralizing tonal features that matter only to human readers; they are reshaping disclosures not for human listeners but for an algorithmic audience.
Supported by Bentley Research Council and Faculty Affairs Committee grants.
Bond Investors' Trading Horizon and the Cost of Debt
Abstract
This paper examines the effects of institutional bond ownership on the cost of debt. Empirical evidence shows that higher long-term institutional bond ownership lowers the cost of debt, whereas short-term bond ownership increases capital supply uncertainty and debt cost. These findings are robust to controlling for bond/investor characteristics and using investors’ funding structure as an instrumental variable. The results suggest that short-term bond investors’ capital supply uncertainty contributes to fragility problems in the corporate bond market. Conversely, long-term institutional bond ownership enhances corporate governance, thereby lowering the cost of debt.
Presented at Sydney Banking and Financial Stability Conference, SFA, AFA PhD Session, FMA, FMA European.
Information Risk, Default Risk, and Callable Bond Yield Spreads
Abstract
Theory suggests that issuing callable bonds conveys private information and reduces information risk. We examine the impact of information risk on yield spreads for both straight and callable bonds. Our analysis reveals that as information risk or credit rating deteriorates, the difference in the sensitivity of changes in yield spreads to interest rates between straight and callable bonds shrinks. The results are similar when using equity volatility as an alternative proxy of default risk. Overall, there is evidence of a negative relation between call premium and default/information risk, which has not been explored in the literature.
Modeling Repo Collateral and Counterparty Risks
Abstract
We propose a dynamic search-based asset pricing model with collateral and counterparty risks to examine the role of these risks in the repo market and the secondary market for collateral. We show that collateral and counterparty risks increase expected loss in repo transactions, discourage trading activity, and reduce demand for collateral. Funding costs in the repo market and yield spreads of bond collateral increase with these risks and these effects magnify in times of stress.
FMA Annual Meeting Best Paper Award in Investments, semifinalist (2018). Presented at FIRS, MFA, FMA European.
Dual Ownership and Investment Decisions: Evidence from Corporate Acquisitions
Abstract
This paper shows that firms with higher equity ownership by dual holders are less likely to make large and public acquisitions. We show that the relation between dual ownership and acquisition decisions is causal using investors’ reaching for yield preference as an external shock to dual ownership. Firms with high dual ownership are less likely to make high-risk, low-quality, and shareholder value-destroying acquisitions. Dual ownership is also associated with favorable market reactions to acquisition announcements and superior operating performance in the postacquisition period. Overall, these results indicate that dual ownership improves corporate investment decisions by mitigating the conflict of interest between shareholders and bondholders and managerial agency problems.
Presented at FMA (2022).
Publications
The Effect of Institutional Herding on Stock Prices: The Differentiating Role of Credit Ratings
Abstract
This paper investigates the impact of institutional herding on stock price formation, conditional on firms’ credit ratings, using 13F data from 1986 to 2019. In line with the current literature, we find herding intensity is driven by past returns consistent with momentum trading; however, we also find that herding is more sensitive to past returns for non-investment grade (NIG) stocks than investment grade (IG) stocks, resulting in a market bifurcation. We then examine the price impact of these trades and find that herding in NIG equities enhances price discovery. One plausible explanation is that information gradually diffuses within non-investment grade stocks, and herding behavior strengthens information discovery. Finally, we show both momentum-triggered herding and non-momentum-triggered herding contribute to price discovery among non-investment grade stocks.
Teaching
Investments, corporate finance, fixed income, financial markets, and risk management. Courses connect theory to practice through the Bentley Trading Room and Bloomberg, Excel modeling, market-news briefings, and team projects judged by industry professionals. Featured in Bentley's 2026 Know Your Faculty series.
Bentley University · Instructor
- FI 623 · Investments Graduate, 2023–present
- FI 306 Honors · Financial Markets and Investment 2020–2024
- FI 118 · Introduction to Finance 2023, 2026
- FI 305 · Principles of Accounting and Finance 2025
University at Buffalo · Instructor
- MGF 405 · Advanced Corporate Finance 2018–2019
“I really enjoyed the projects, as they were stimulating and forced us to learn what we did in class. The presentation in front of industry professionals was a very meaningful experience.”
FI 623 Investments, Fall 2025“The structure of the class is well planned. It provides a lot of hands-on learning through the projects, and the in-class news briefs create insightful discussions around what is happening in the market.”
FI 623 Investments, Spring 2025“I like how the class makes you think conceptually about the topics we learn, and then how we use examples to apply these concepts using Excel.”
FI 623 Investments, Spring 2025“The thing I most liked about the class is the Excel model she makes and explains to us.”
FI 305 Principles of Accounting and Finance, Fall 2025“I enjoyed the Bloomberg project. Going into Bloomberg and analyzing a stock and learning the ins and outs was a really good experience.”
FI 118, Spring 2026“Li Ting wants her students to succeed. She used real-life and current economic scenarios, making the class intuitive and fun.”
MGF 405 Advanced Corporate Finance, University at Buffalo
Teaching with AI